

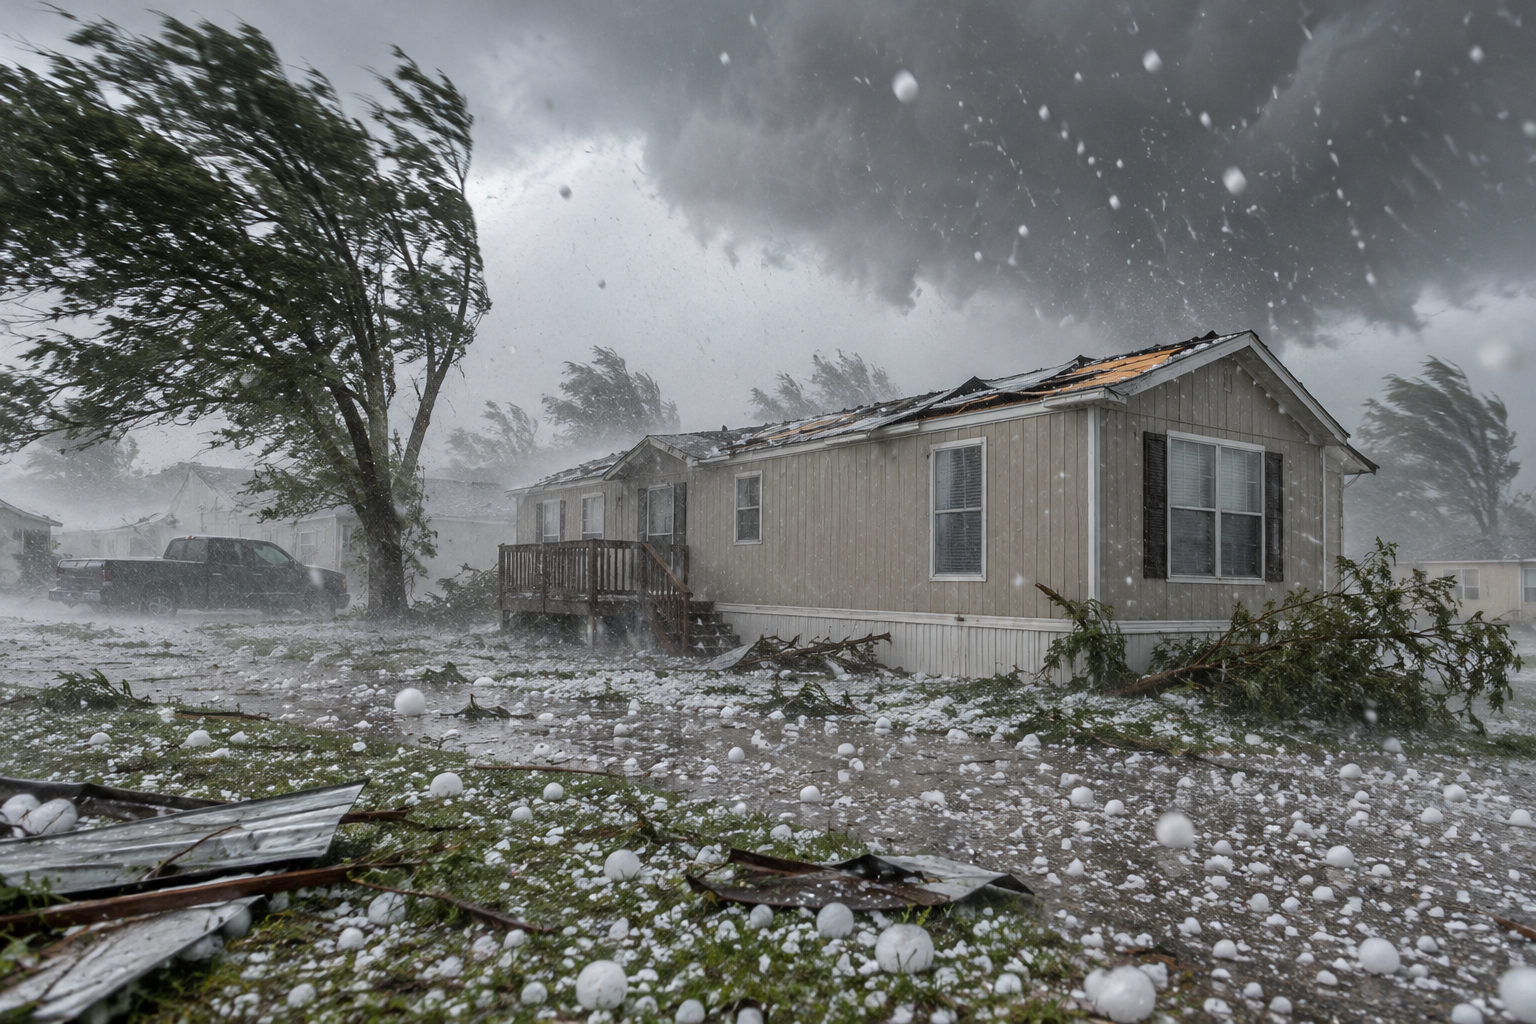
Most standard manufactured home insurance policies in Texas do cover wind and hail damage, but south Texas homeowners need to review the details carefully. Your policy may have a separate wind and hail deductible, and homes in designated coastal catastrophe areas may need Texas Windstorm Insurance Association (TWIA) coverage instead. Flood damage is handled differently and is generally excluded from a standard manufactured home policy.
At Mr. Mobile Home Insurance in McAllen, TX, we help homeowners across south Texas understand how their coverage is structured before storm season—not after damage has occurred.
How Wind and Hail Coverage Works on an HO-7 Policy
A typical Manufactured Home Insurance
policy is often written on an HO-7 form, which is designed specifically for manufactured and mobile homes. Depending on the policy and endorsements selected, coverage can help pay to repair or replace the home after covered weather losses, including wind, hail, lightning, and certain hurricane-related wind damage.
Coverage commonly extends to the dwelling itself and may also include personal property, other structures, loss of use, and personal liability. The exact protection available depends on the policy’s limits, valuation method, deductible, exclusions, and whether windstorm coverage is included or handled through a separate policy.
That is why it is important not to assume that “home insurance” automatically means every type of storm damage is covered. Mr. Mobile Home Insurance can review the declarations page and explain what your specific policy covers.
Standard Deductible vs. Wind and Hail Deductible
A deductible is the amount you pay out of pocket before insurance contributes to a covered claim. Your standard all-perils deductible may apply to losses such as fire, theft, or certain accidental damage. Wind and hail claims, however, may be subject to a separate deductible.
In south Texas, that separate deductible matters. It may be a flat dollar amount or a percentage of the dwelling coverage limit. For example, a percentage deductible can create a much larger out-of-pocket cost than homeowners expect after a major windstorm. A higher deductible may reduce the premium, but it should still be an amount your household could realistically manage after a storm.
Before buying or renewing coverage, compare the deductible language—not just the price. Our Insurance Rate Factors
page is a helpful starting point for understanding why deductibles, location, home age, condition, and coverage choices can affect your rate.
When Does TWIA Apply to Manufactured Homes?
The Texas Windstorm Insurance Association (TWIA)
is a residual insurance option for eligible properties in designated coastal catastrophe areas when wind and hail coverage is not available through the private market. TWIA can insure eligible manufactured homes for windstorm and hail, but it is not automatically added to every policy.
For a TWIA manufactured home policy, the home generally must be in the designated coverage area, meet eligibility and underwriting requirements, and have documentation showing it complies with applicable windstorm construction standards. Applicants also generally need to show that they were unable to obtain the needed wind and hail coverage from an authorized insurer writing in the area.
Cameron County is one of the designated first-tier coastal counties where TWIA may be relevant. If your manufactured home is in Brownsville, Port Isabel, South Padre Island, or elsewhere in Cameron County, it is especially important to confirm whether wind and hail protection is included with your home policy or must be placed separately.
Hidalgo County and South Texas Storm Exposure
Hidalgo County is not one of TWIA’s designated first-tier coastal counties, but that does not mean wind and hail risk disappears. McAllen, Edinburg, Mission, Weslaco, and communities throughout Hidalgo County
can experience damaging thunderstorms, straight-line winds, hail, and tropical systems moving inland from the Gulf.
For manufactured home owners in Hidalgo County, wind and hail coverage is often included in the standard policy, subject to the policy terms and deductible. Still, each policy is different. A homeowner should verify that windstorm damage is not excluded, that the dwelling limit reflects current replacement costs, and that attached features or belongings have the coverage they need.
This is the practical difference between simply having manufactured home insurance in Texas and having coverage that fits the risks of south Texas.
Does Mobile Home Insurance Cover Hurricane Damage?
The answer is: it depends on what caused the damage.
When people ask, “Does mobile home insurance cover hurricane damage?” they are often describing multiple types of loss at once. Hurricane-force wind and wind-driven hail may be covered by the manufactured home policy or a separate windstorm policy, such as TWIA when applicable. Damage caused by rising water, storm surge, overflow, or flooding is generally not covered by a standard manufactured home policy or TWIA wind policy.
Flood insurance is a separate coverage decision. Even homes outside a mapped high-risk flood zone can flood during a tropical weather event. Reviewing wind, flood, and homeowners coverage together helps prevent a damaging gap in protection.
What to Expect After a Hurricane or Major Hailstorm
After a covered loss, protect people first, take photos and videos of the damage when safe, and make reasonable temporary repairs to prevent additional damage. Keep receipts for emergency measures, avoid permanent repairs until the carrier has had an opportunity to inspect when possible, and report the claim promptly.
Your carrier will review the claim, inspect the damage, apply the appropriate deductible, and determine payment based on the policy’s covered causes of loss, limits, and settlement terms. A storm claim can be less stressful when you already know which carrier handles wind, what your deductible is, and how to reach them. Keep your policy information accessible, including the details on how to Make a Payment
so an avoidable lapse does not create a problem at the worst possible time.
Why Review Coverage Before Storm Season
Storm season is not the time to discover that your wind deductible is higher than expected or that your coastal home requires separate windstorm insurance for manufactured homes. Coverage may be restricted when a named storm is approaching, so waiting until a hurricane is in the Gulf can leave homeowners with limited options.
Mr. Mobile Home Insurance helps families in McAllen, the Rio Grande Valley, Cameron County, Hidalgo County, and across south Texas evaluate their coverage structure ahead of severe weather. Review the dwelling limit, wind and hail deductible, personal-property protection, flood needs, and any required TWIA arrangement before the forecast turns serious. You can also learn more about common policy features in our HO-7 Policy Guide.
FAQ
Does manufactured home insurance cover wind and hail damage in Texas?
Often, yes. Standard manufactured home policies commonly include wind and hail, but the policy may carry a separate wind and hail deductible or an exclusion for certain coastal locations.
Does TWIA cover manufactured homes?
TWIA may provide windstorm and hail coverage for eligible manufactured homes in its designated catastrophe area, including Cameron County, when private-market coverage is unavailable and other eligibility requirements are met.
Does TWIA cover flood damage?
No. TWIA is for windstorm and hail coverage, not flood damage. Flood insurance must be purchased separately.
Why is the wind and hail deductible different?
Wind and hail losses can be frequent and severe in storm-prone areas. Insurers may apply a separate deductible to these claims, which can be a dollar amount or percentage of the home’s insured value.
How can I check whether my coverage is right for south Texas?
Review your policy declarations page and ask about wind and hail coverage, deductibles, flood exclusions, dwelling limits, and whether a separate windstorm policy is needed. Not sure your wind and hail coverage is structured right for south Texas? Get a free quote from Mr. Mobile Home Insurance.